
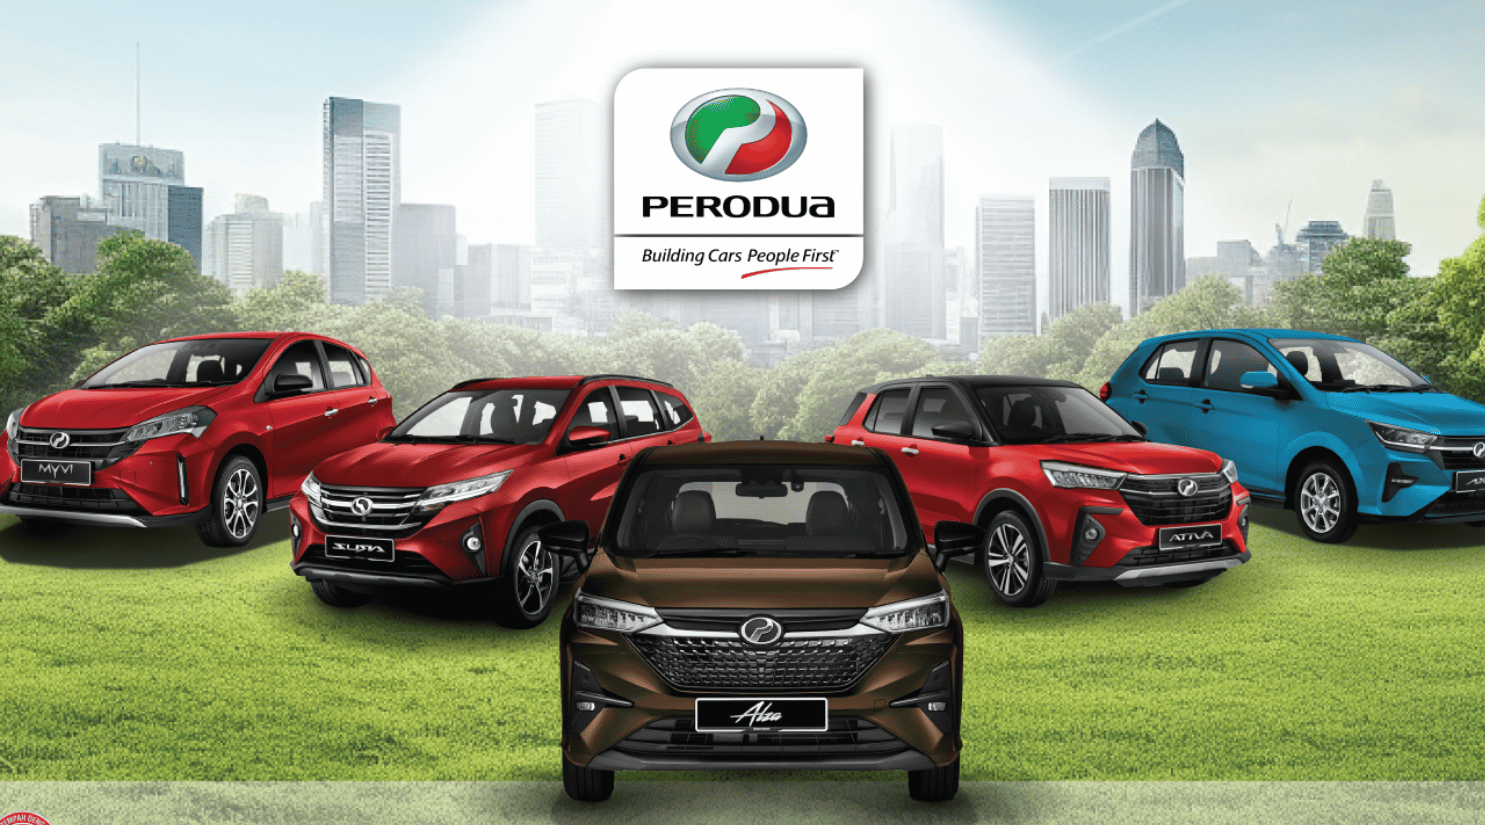
Driving home a brand-new Perodua is a major milestone for many Malaysians. Whether you are picking up an economical Axia for city commuting, a spacious Bezza sedan, Malaysia’s iconic Myvi, or a 7-seater Alza MPV for family trips, calculating your monthly commitment before visiting the showroom ensures a seamless buying journey.
Understanding how bank interest rates, down payments, and loan tenures interact allows you to pick the right variant while staying comfortably within your monthly budget.
Using a Perodua loan calculator helps you estimate your monthly instalments, break down interest calculations, and secure fast financing through Perodua Cheras.
How Hire Purchase Car Loans Work in Malaysia
In Malaysia, auto financing is structured under a Hire Purchase (HP) agreement featuring a Flat Interest Rate. Unlike variable housing mortgages where interest reduces as the principal balance drops, flat-rate auto loans calculate interest based on the initial principal loan amount across the entire repayment period.
The fundamental formula used by any Perodua loan calculator follows these basic steps:
- Loan Amount = On-The-Road (OTR) Price – Down Payment
- Total Interest Paid = Loan Amount x (Annual Interest Rate / 100) x Loan Tenure in Years
- Total Repayment Amount = Loan Amount + Total Interest Paid
- Monthly Instalment = Total Repayment Amount / Loan Tenure in Months
Estimated Perodua Monthly Instalment Reference Table (2026)
Below is an estimated monthly payment breakdown for popular Perodua models based on a standard 10% down payment at an estimated 2.50% p.a. flat interest rate across 5-year, 7-year, and 9-year tenures:
| Model & Variant | Estimated OTR Price (RM) | 10% Down Payment (RM) | Loan Amount (RM) | 5-Year Tenure (RM/mo) | 7-Year Tenure (RM/mo) | 9-Year Tenure (RM/mo) |
| Perodua Axia 1.0 G (D-CVT) | RM 33,900 | RM 3,390 | RM 30,510 | RM 572 | RM 427 | RM 346 |
| Perodua Bezza 1.3 Premium X | RM 43,980 | RM 4,398 | RM 39,582 | RM 742 | RM 553 | RM 449 |
| Perodua Myvi 1.5 H (D-CVT) | RM 54,900 | RM 5,490 | RM 49,410 | RM 926 | RM 691 | RM 560 |
| Perodua Ativa 1.0 Turbo X | RM 62,500 | RM 6,250 | RM 56,250 | RM 1,055 | RM 786 | RM 638 |
| Perodua Alza 1.5 H | RM 68,000 | RM 6,800 | RM 61,200 | RM 1,148 | RM 856 | RM 694 |
| Perodua Aruz 1.5 AV | RM 77,900 | RM 7,790 | RM 70,110 | RM 1,315 | RM 980 | RM 795 |
(Note: Calculated estimates are for reference only. Actual bank interest rates vary between 2.30% and 3.50% based on individual credit profiles, loan tenure lengths, and Bank Negara Malaysia OPR settings.)
4 Key Factors Influencing Your Perodua Monthly Payment
When testing different figures in a Perodua loan calculator, adjusting these four variables directly impacts your monthly commitment:
1. On-The-Road (OTR) Price & Promotional Rebates
Official cash rebates, seasonal promotional discounts, and trade-in support reduce the total required loan amount, directly lowering your monthly payment.
2. Down Payment Percentage
Putting down a higher upfront deposit (e.g., 20% instead of the standard 10%) reduces your principal balance, significantly cutting down total interest paid over the loan tenure.
3. Loan Tenure Length (Years)
Malaysian financial institutions offer Hire Purchase tenures ranging from 1 to 9 years (12 to 108 months). While choosing a 9-year tenure provides the lowest monthly payments, selecting a 5-year or 7-year tenure saves substantial interest costs in the long run.
4. Credit Profile & Bank Interest Rates
Major financial institutions (Maybank, Public Bank, CIMB, RHB, Hong Leong Bank) assign interest rates based on your monthly income, employment stability, and Central Credit Reference Information System (CCRIS) record.
Understanding Your Debt Service Ratio (DSR)
Before approving a Hire Purchase loan, bank credit evaluators calculate your Debt Service Ratio (DSR) to ensure your commitments remain manageable:
DSR (%) = [ Total Monthly Commitments (Housing Loan + Existing Loans + Proposed Car Loan) / Nett Monthly Income ] x 100
- Bank Acceptance Benchmark: Most banks prefer a total DSR below 60% to 70%.
Golden Rule for Car Ownership: To maintain financial balance, your new car’s monthly instalment should ideally
consume no more than 20% to 25% of your total nett take-home income.
Financing Comparison: 5-Year vs. 7-Year vs. 9-Year Loan
Monthly Instalment Amount
A 5-Year Loan requires higher monthly instalments. A 7-Year Loan provides a balanced, mid-range monthly payment. A 9-Year Loan offers the lowest possible monthly payment.
Total Interest Paid
A 5-Year Loan keeps cumulative interest costs to a minimum. A 7-Year Loan incurs moderate total interest. A 9-Year Loan incurs the highest total interest charges over time.
DSR Approval Eligibility
A 5-Year Loan requires higher nett monthly income to pass bank DSR benchmarks. A 7-Year Loan offers an accessible compromise for most working adults. A 9-Year Loan lowers monthly DSR requirements for easier qualification.
Frequently Asked Questions (FAQ)
Standard Hire Purchase loans require a minimum 10% down payment. However, zero-downpayment (100% full loan) packages are available for civil servants, fresh graduates, and qualified applicants under specialized bank schemes.
Salaried employees must submit a copy of their MyKad, driver’s license, latest 3 months’ payslips, and 3 months’ bank statements. Self-employed individuals need to provide SSM business registration certificates and 6 months’ company bank statements.
Yes! Fresh graduates holding a diploma or degree with an official employment offer letter can qualify for graduate full-loan schemes without needing a guarantor, provided the monthly instalment meets bank income requirements.
Bank interest rates depend on individual credit scoring, loan tenure duration, down payment ratios, and current promotional campaigns. Perodua Cheras submits applications to multiple panel banks to secure the lowest available rate for your profile.
Plan Your Purchase with Perodua Cheras Today
Estimating your monthly payment using a Perodua loan calculator gives you the clarity to select a model that aligns with your financial goals.
At Perodua Cheras, our dedicated sales team helps you calculate accurate monthly instalments, maximize trade-in values for your current car, and apply for competitive bank rates.
Ready to calculate your exact monthly payment? Contact Perodua Cheras today to request a custom price quotation and schedule your test drive!
Calculate Your Monthly Instalment Here!

3 comments
Pingback:
Perodua Ativa Pink Edition Promo 2026: How to Win OnePingback:
Perodua QV-E Rebate 2026: Now From RM53,499Pingback:
Perodua Malaysia Day Deals 2026: Rebates Up to RM10k